All industry funding options
Support your manufacturing business with finance designed to help with machinery, equipment, cash flow, or expansion.
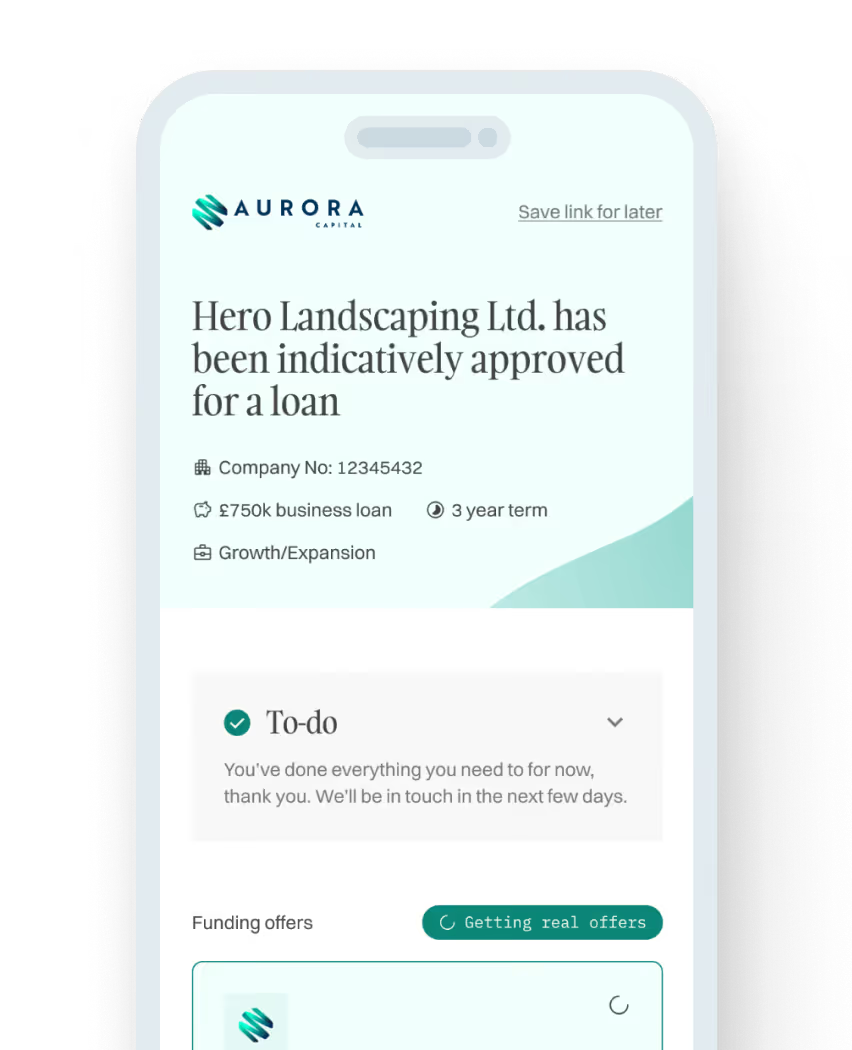
Our LendTech Platform lets you:

Check Eligibility in 30 seconds
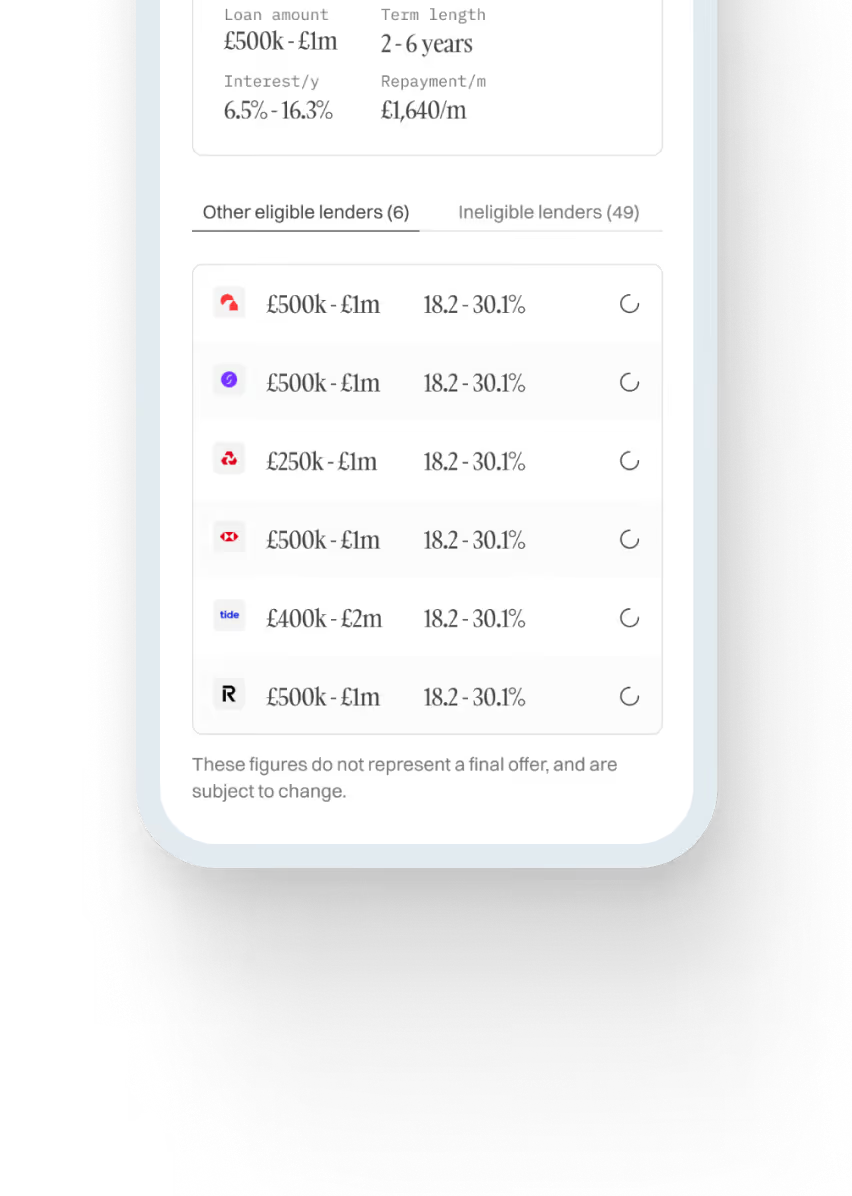
Match with 50+ lenders
Get indicative offers in 5 mins
Apply in minutes
Free, no-obligation quote
No effect on credit score

Manufacturers often need to spend big before their finished product generates revenue. Materials, machinery and staff all need funding during the production process. When customers then take 30, 60 or 90 days to settle invoices, even a healthy order book can put pressure on cash flow.
Manufacturing finance can help manage those demands without delaying investment. Whether you are buying new equipment, taking on larger orders or looking for breathing room between production and payment, there may be a funding option that fits.
What is manufacturing finance?
Manufacturing finance is business funding used to support the costs of producing goods and running a manufacturing operation. It can cover materials, machinery, working capital or expansion.
Rather than one specific loan, manufacturing finance can include fixed business loans, asset finance, invoice finance and reusable credit facilities. Some provide a lump sum. Others fund production costs as they arise or release cash from unpaid invoices.
The right structure depends on what you are funding, when you expect money to come back into the business and how comfortably you can manage repayments.
What types of finance are available to manufacturers?
There are several ways to fund a manufacturing business. Each is designed for different costs and trading patterns.
Unsecured business loans
An unsecured loan provides a lump sum without requiring property or equipment as security. It may cover working capital, stock, recruitment or growth. Lenders will still assess affordability and may ask for a personal guarantee.
Secured business loans
Secured loans use an asset, often property, as security and may suit larger investments or longer terms. The asset is at risk if repayments cannot be maintained.
Asset finance
Asset finance helps spread the cost of machinery, equipment or vehicles over an agreed period. The structure and ownership arrangements depend on the finance agreement.
Invoice finance
If you supply businesses on credit terms, invoice finance may release part of eligible unpaid invoices before customers pay.
Revolving credit facilities
A revolving credit facility provides an agreed borrowing limit that you can draw from, repay and reuse. It can help you meet changing production costs without applying for a separate loan each time. Interest is generally charged on the funds you use rather than the full limit.
What can manufacturing finance be used for?
Manufacturing funding can support both planned investment and everyday operational costs. Common uses include:
Increasing production capacity
A new contract may mean extra shifts, staff or production. Business loans for manufacturers can cover costs before revenue arrives.
Modernising your operation
Machinery upgrades or automation can increase output and reduce downtime. Finance spreads the cost while new equipment is put to work.
Keeping operations moving
Materials, utilities, wages and supplier invoices all need paying on time. Funding can help protect working capital during periods when cash is tied up in stock, unfinished goods or outstanding customer invoices.
It may also be possible to use manufacturing business loans to refinance existing borrowing, provided the lender accepts the purpose and the new agreement offers a suitable fit.
How can I finance new machinery or equipment?
A new CNC machine or packaging line is a major commitment. Consider its price, working life and contribution to revenue or efficiency.
Asset finance is often worth exploring because it is designed around the equipment itself. Depending on the agreement, hire purchase may offer a route to ownership after the final payment, while leasing can provide use of the equipment without necessarily owning it.
A business loan may suit outright purchases or projects that include installation and training. Compare the total cost, ownership terms and any deposit or security requirements before deciding.
Can I get funding to buy materials or stock?
Yes. Raw materials, components and packaging require cash before production begins. Large orders may be profitable, but they can still stretch working capital when suppliers need paying ahead of your customers.
An unsecured business loan may suit a specific stock purchase or production run. A revolving credit facility may be more useful when material orders happen regularly and the amount you need changes from month to month.
If you already invoice reliable business customers, invoice finance may also help release cash from outstanding invoices to put towards the next order. The best approach depends on your payment terms and the time between buying materials and getting paid.

Get a free, no obligation quote
Apply in minutes, there’s no impact on your credit score and you’ll get a free, no obligation personalised quote in hours. Regulated by the FCA: 831395
How much would you like to borrow?
Thank you! Your submission has been received!
Oops! Something went wrong while submitting the form.
Prefer to talk? Call us on 01371870815


How the process works
[1]
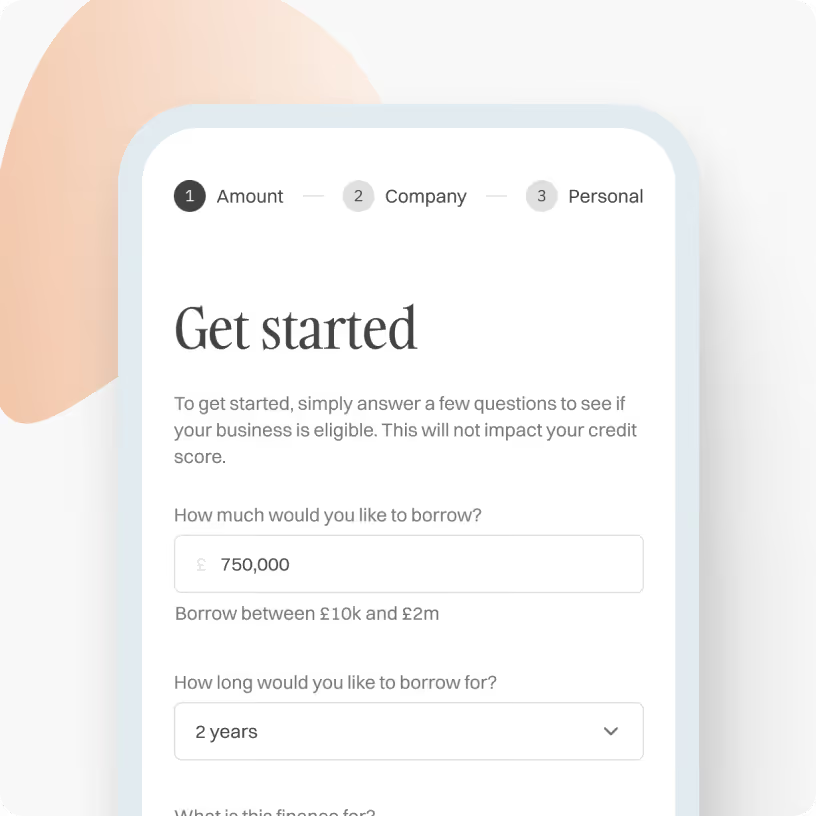
Enquire and check eligibility
Enquire in under 30 seconds to find out if your business is eligible for funding. We only need basic information about your business.
Check eligibility now
[2]
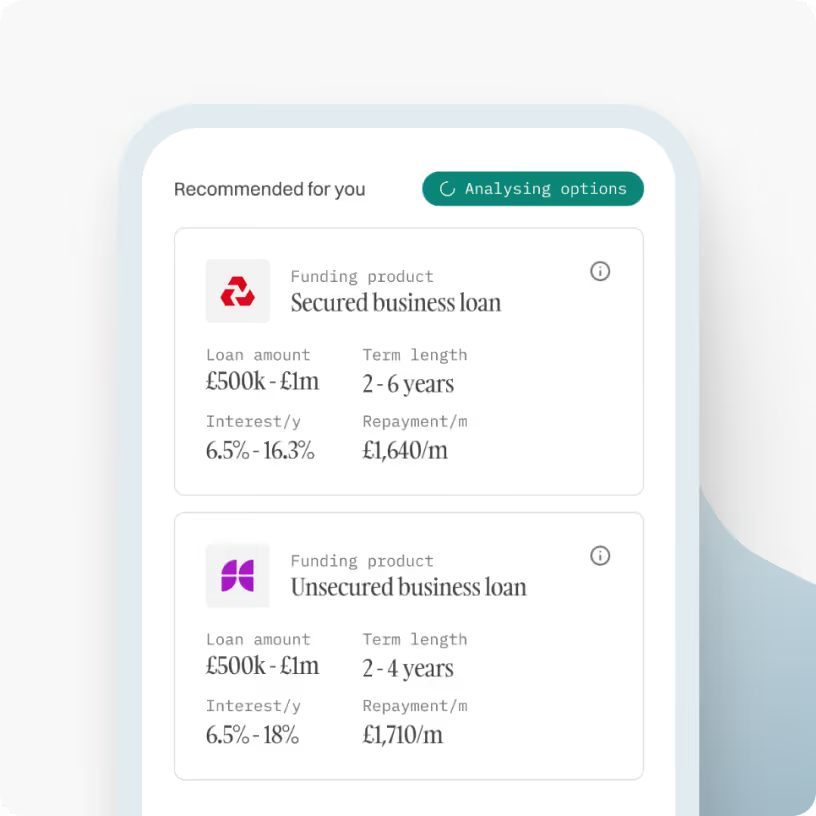
Get matched to lenders
Our LendTech technology will compare over 50 lenders and match you with the most suitable finance options.
Check eligibility now
[3]
Obtain funding in 48 hours
Once you have fully submitted your proposal, one of our funding specialists will discuss the available options and help get you funded.
Check eligibility now
No items found.
No items found.
No items found.
Get a quote, fast
Lending period
Thank you! Your submission has been received!
Oops! Something went wrong while submitting the form.
Thank you! Your submission has been received!
Oops! Something went wrong while submitting the form.

Growth Guarantee Scheme
An unsecured business loan backed by the government. Ideal for businesses looking to grow and expand.
- Amount£25,001 to £750,000
- TermsUp to 6 year terms
- InterestFrom 10% per annum
Start growing


Unsecured Business Loans
A flexible, unsecured business loan with no security on assets or property. Ideal for growth, cashflow or working capital needs.
- Amount£10,000 to £750,000
- TermsUp to 6 year terms
- InterestFrom 6.9% per annum
Get unsecured loan

Asset Finance
Whether you are looking to purchase machinery, equipment or vehicles, this could be the ideal solution for your business.
- Amount£5,000 to £750,000
- TermsUp to 6 years
- InterestFrom 6% per annum
Finance assets

Revolving Credit Facilities
Looking to have a facility where you can drawdown funds when and if you require them, this could be the perfect facility for you.
- Amount£1,000 to £1,000,000
- TermsUp to 3 years
- InterestFrom 1.5% per month
Access credit line

VAT/Tax Loans
Have an upcoming Vat or Tax bill? This could be the perfect facility to keep cashflow healthy and never have to make a big chunky HMRC payment again.
- Amount£10,000 to £750,000
- TermsUp to 1 year term
- InterestFrom 1% per month
Get VAT loan

Merchant Cash Advances
A perfect solution for businesses that take over £10k per month in card/online sales. Rather than paying a fixed monthly payment, repayments are taken as a % of future card sales.
- Amount£10,000 to £750,000
- TermsVariable
- InterestNo APR
Get cash advance

Secured Business Loans
Are you a new start-up business or are you looking to invest a larger sum into your business? By using a property as security, we can lend larger amounts over longer terms.
- Amount£25,000 to £2,000,000
- TermsUp to 15 years
- InterestFrom 10% per annum
Get secured loan

Small Business Loans
Compare small business loans to assist with purchasing stock, upgrading equipment, or just general working capital requirements.
- Amount£10,000 to £750,000
- TermsUp to 6 years
- InterestFrom 6.9% per annum
Get small business loan

Guides to help you make the best financial decisions
Compare business funding options today, quickly and easily
Browse our range of business funding options to find out more and discover the one that best suits your business.
Compare funding options
Prefer to chat? Call us on 01371870815 to speak to our experts.