No items found.

All business needs options
Machinery Finance
- Invest in new or upgraded machinery with flexible business finance. Compare funding options from UK lenders to find a solution that suits your business.
Our LendTech platform lets you:

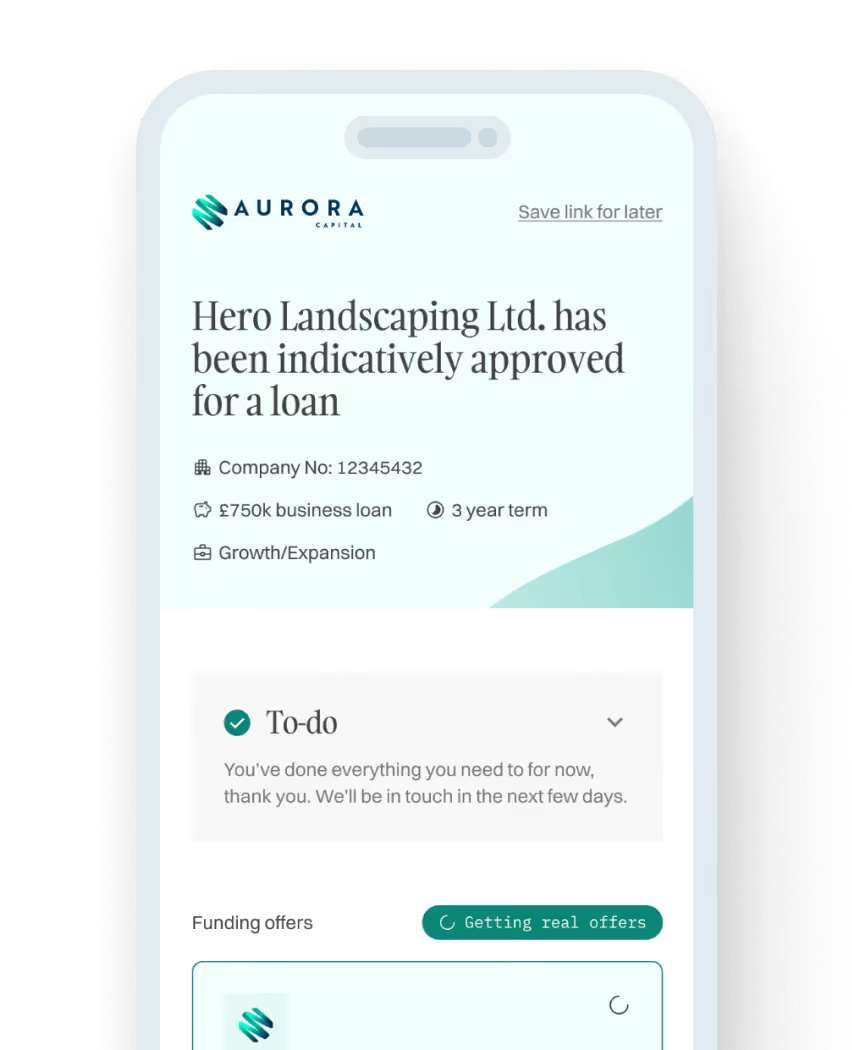
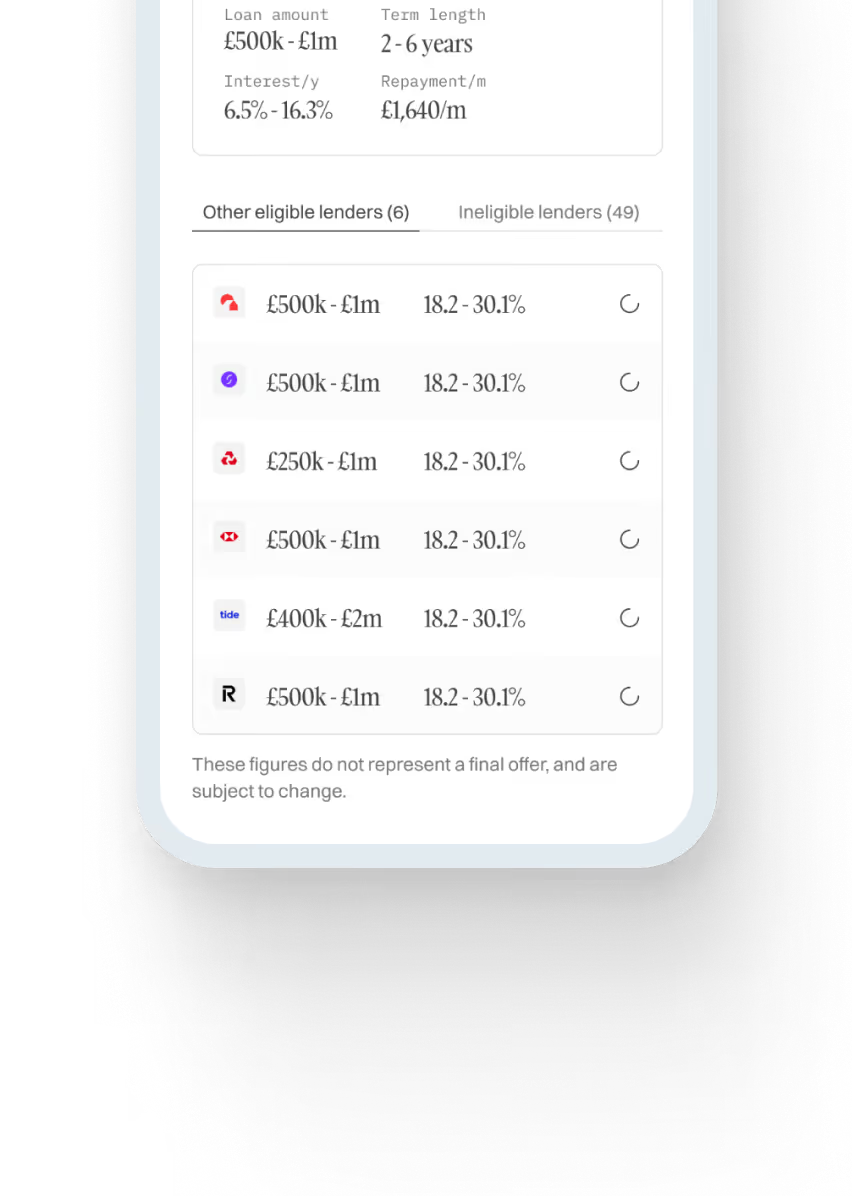
Check eligibility in 30 seconds
Match with 50+ lenders
Get indicative offers in 5 mins
Check eligibility
Applying won't affect your credit score
Apply in minutes
Free, no-obligation quote
No effect on credit score
Get a quote, fast
Lending period
Thank you! Your submission has been received!
Oops! Something went wrong while submitting the form.
Thank you! Your submission has been received!
Oops! Something went wrong while submitting the form.
Whether you rely on production lines, workshop equipment or specialist plant, the right machinery can improve capacity and productivity. But replacing or upgrading it can carry a significant upfront cost.
Machinery finance can help you invest without using all your available cash at once. By spreading the cost over an agreed period, you can keep working capital available for wages, materials and other day to day commitments.
What is machinery finance?
Machinery finance is a type of business funding used to purchase, replace or upgrade equipment. Rather than paying the full cost upfront, your business makes repayments over an agreed term.
It is often arranged through asset finance, which is designed around the machinery itself. Depending on the agreement, you may own the equipment at the end of the term or use it through a lease. A conventional business loan can also be used to fund a machinery purchase.
Plant and machinery finance can be useful for businesses that need expensive equipment to operate but want to protect cash flow while investing in growth.
How does machinery finance work?
The process usually starts by identifying the machine you need and getting a quote from the supplier. The lender then assesses your business, the equipment and the proposed repayments before making an offer.
If the facility is approved, the finance provider typically funds the purchase and your business makes regular payments over the agreed term. The exact structure depends on whether you choose hire purchase, leasing or another form of machinery financing.
When comparing offers, consider any deposit, fees, total repayable amount, maintenance responsibilities and what happens when the agreement ends.
What types of machinery can be financed?
Machinery loans can support a broad range of equipment across UK industries. Common examples include:
- Manufacturing machinery such as presses, cutting equipment and production lines
- Engineering equipment such as CNC machines, fabrication tools and testing systems
- Construction plant such as excavators, loaders and specialist site machinery
- Agricultural machinery such as tractors, harvesters and processing equipment
- Packaging, printing and food production equipment
Whether an asset qualifies will depend on the lender, its age and condition, its value and how readily it can be resold. Some lenders specialise in particular types of plant and machinery.
Can you get finance for used machinery?
Yes. Machinery finance UK lenders may consider both new and used equipment. Buying used machinery can reduce the initial investment, especially when a reliable machine still has plenty of working life left.
However, the lender may want more information about the equipment before agreeing to fund it. This could include its age, service history, condition, supplier and estimated resale value.
Older or highly specialised machinery may have fewer funding options or different terms. It is worth checking eligibility before committing to a purchase, particularly if you are buying from a private seller or arranging an auction purchase.
What is the difference between machinery finance, leasing and hire purchase?
Machinery finance is the wider term for funding equipment. Machinery leasing and machinery hire purchase are two common ways of structuring it.
Machinery hire purchase
With hire purchase, the finance provider owns the machine while you make instalments. Once you have completed the payments and any applicable purchase option fee, ownership transfers to your business. This can suit equipment you expect to use for many years.
Machinery leasing
With a lease, you pay to use machinery for an agreed period rather than buying it outright at the outset. Depending on the agreement, you may return the asset, extend the lease or explore another end of term option. Leasing can suit businesses that want to replace equipment regularly.
Business machinery loan
A conventional business loan provides a lump sum to buy equipment. It can be useful when you want to purchase the asset directly, although the loan may have different eligibility, security and repayment requirements.
The right choice depends on whether ownership, lower upfront costs or flexibility matters most to your business.

Get a free, no obligation quote
Apply in minutes, there’s no impact on your credit score and you’ll get a free, no obligation personalised quote in hours. Regulated by the FCA: 831395
How much would you like to borrow?
Thank you! Your submission has been received!
Oops! Something went wrong while submitting the form.
Prefer to talk? Call us on 01371870815
How the process works
[1]
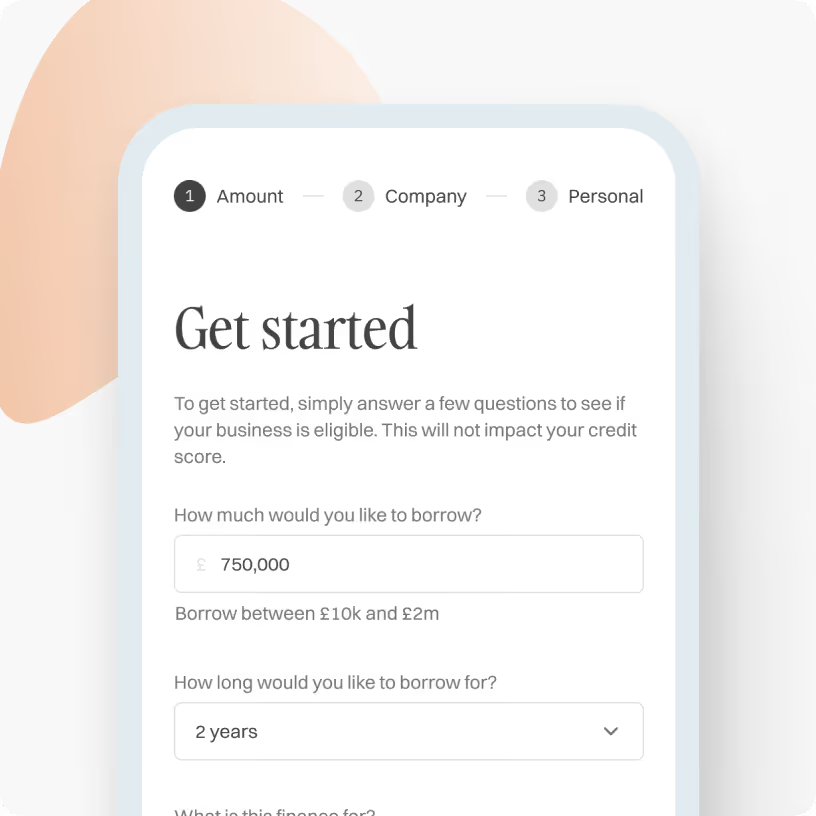
Enquire and check eligibility
Enquire in under 30 seconds to find out if your business is eligible for funding. We only need basic information about your business.
Check eligibility now
[2]
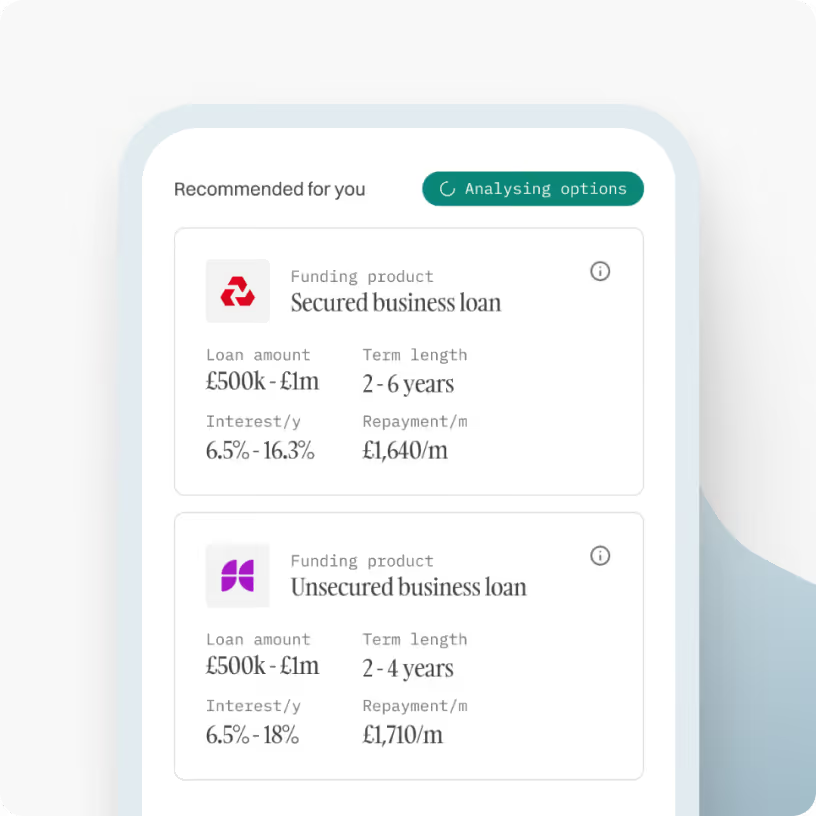
Get matched to lenders
Our LendTech technology will compare over 50 lenders and match you with the most suitable finance options.
Check eligibility now
[3]
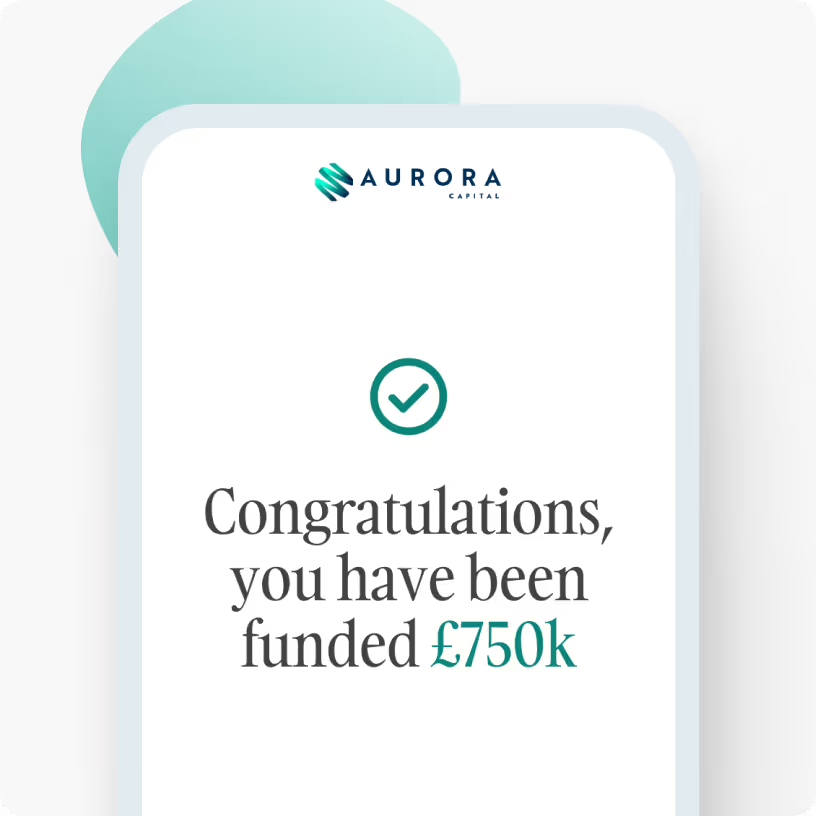
Obtain funding in 48 hours
Once you have fully submitted your proposal, one of our funding specialists will discuss the available options and help get you funded.
Check eligibility now
No items found.
No items found.
No items found.
How much could you borrow?
Thank you! Your submission has been received!
Oops! Something went wrong while submitting the form.
Apply in minutes
Free, no-obligation quote
No effect on credit score

Growth Guarantee Scheme
An unsecured business loan backed by the government. Ideal for businesses looking to grow and expand.
- Amount£25,001 to £750,000
- TermsUp to 6 year terms
- InterestFrom 10% per annum
Start growing


Unsecured Business Loans
A flexible, unsecured business loan with no security on assets or property. Ideal for growth, cashflow or working capital needs.
- Amount£10,000 to £750,000
- TermsUp to 6 year terms
- InterestFrom 6.9% per annum
Get unsecured loan

Asset Finance
Whether you are looking to purchase machinery, equipment or vehicles, this could be the ideal solution for your business.
- Amount£5,000 to £750,000
- TermsUp to 6 years
- InterestFrom 6% per annum
Finance assets

Revolving Credit Facilities
Looking to have a facility where you can drawdown funds when and if you require them, this could be the perfect facility for you.
- Amount£1,000 to £1,000,000
- TermsUp to 3 years
- InterestFrom 1.5% per month
Access credit line

VAT/Tax Loans
Have an upcoming Vat or Tax bill? This could be the perfect facility to keep cashflow healthy and never have to make a big chunky HMRC payment again.
- Amount£10,000 to £750,000
- TermsUp to 1 year term
- InterestFrom 1% per month
Get VAT loan

Merchant Cash Advances
A perfect solution for businesses that take over £10k per month in card/online sales. Rather than paying a fixed monthly payment, repayments are taken as a % of future card sales.
- Amount£10,000 to £750,000
- TermsVariable
- InterestNo APR
Get cash advance

Secured Business Loans
Are you a new start-up business or are you looking to invest a larger sum into your business? By using a property as security, we can lend larger amounts over longer terms.
- Amount£25,000 to £2,000,000
- TermsUp to 15 years
- InterestFrom 10% per annum
Get secured loan

Small Business Loans
Compare small business loans to assist with purchasing stock, upgrading equipment, or just general working capital requirements.
- Amount£10,000 to £750,000
- TermsUp to 6 years
- InterestFrom 6.9% per annum
Get small business loan

Guides to help you make the best financial decisions
Compare business funding options today, quickly and easily
Browse our range of business funding options to find out more and discover the one that best suits your business.
Compare funding options
Prefer to chat? Call us on 01371870815 to speak to our experts.